Wednesday, 15 February 2017

3 Reasons Why You Can’t Save Money Chloe Della Costa

Empty pockets
A broke person unable to save money | iStock.com
Americans today are pretty awful at saving money. Since 25% of Americans said they would give up showers in order to save money, systemic issues like income inequality are likely more to blame than individual habits. But don’t let that be your excuse. Even when you are near-broke, you can still find ways to save here and there. You can cut out unnecessary expenses, eat your meals at home, and make a strict budget and stick to it.
Are you getting bored yet?
It seems that for some people, no matter how many articles they read, no matter how many advisers they meet with, today’s wants simply outweigh tomorrow’s needs. That’s not to say there aren’t people who have money troubles for no fault of their own. But if your steady income is accompanied by a history of poor money management, unpaid debts, and bad financial choices in general, chances are good that you’re just a terrible saver.
To help you understand why you can’t seem to put any of your paycheck aside, we’ve outlined some of the reasons people are so inept at saving. If you can understand where you’ve gone wrong, it will help you finally turn things around. Here are the major missteps of the savings-challenged.

1. You keep upgrading your lifestyle

Aston Martin
Fancy ride to the poor house | Aston Martin
When you get a tax refund or a bonus at work, is your first thought to go out and splurge on a luxury? Impulse buying is one of the most dangerous habits consumers can develop, and it can be made even easier by sudden windfalls. This is how people get into the dangerous cycle of unnecessarily living paycheck to paycheck. What happens is you justify each purchase by telling yourself you still have money “left over.” You might think of increased wealth as a chance to seek status symbols or lifestyle upgrades. Instead, use your newly acquired wealth to break free from old habits. If you resist the temptation to spend your entire paycheck, you’ll find that a little security will give you much more freedom than a lifestyle upgrade.

2. You procrastinate

Woman asleep with credit card and laptop
Sleeping instead of taking action | iStock
There’s a reason why “pay yourself first,” is a golden rule of personal finance. It’s because if people don’t set aside money right away, most won’t do it at all. The general idea is this: Take a certain percentage of your paycheck and allocate it to savings, and the remainder is what you’ll be left with to use for bills and other expenses. Bad savers are often procrastinators, so they continuously tell themselves they’ll save later. To take the pressure off, these kinds of consumers can benefit from setting up automatic withdrawals each month. This gives you no choice but to save, so you can stop making excuses to put it off again and again.

3. You think saving is lame

Women with shopping bags
Shopping won’t solve your money problems | iStock.com
Bad savers sometimes claim they like to “live in the now,” rather than prepare for the future. Do you ever feel like you are stuck in the present? It’s often a lot less glamorous and exciting than it sounds. You can’t have much fun living in the present moment if your present always feels like you are running out of money. Savers are actually better equipped to take the occasional spontaneous trip or adventure because they don’t have to wait for their next paycheck every time they want to do something fun. Instead of focusing on what you want in the here and now, and being disappointed when you can’t afford it, start thinking about what you really want. If you can see past your immediate desires, your bigger goals will start to motivate you. Then you’ll see that saving isn’t a chore at all, it’s your ticket to financial freedom.

Culled from Wallstreetcheatsheet

Tuesday, 14 February 2017

Divorce: A Harvard Study Says This Can Crush Your Marriage -Sam Becker


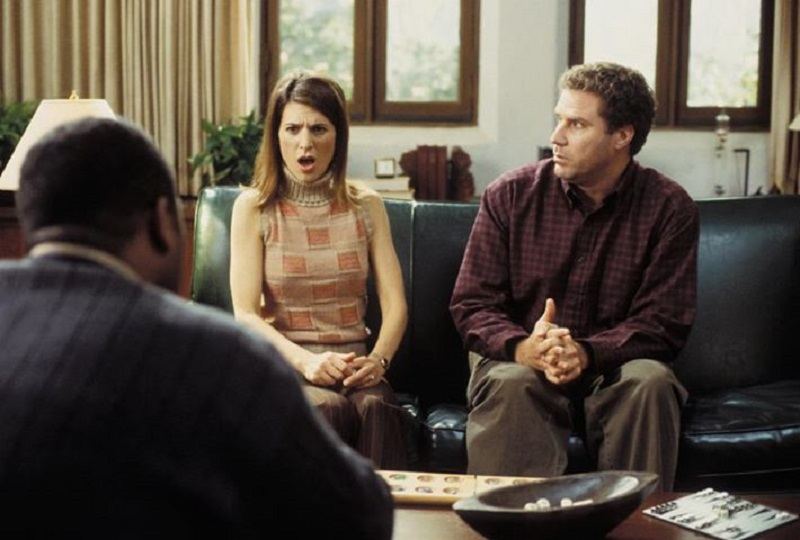
A divorce and marriage counseling session in 'Old School'
A divorce and marriage counseling session in Old School | Source: Dreamworks
Maintaining a long, healthy relationship is one of the biggest challenges people face in life. There are so many factors that can affect the status of a marriage or relationship and so many things that are simply out of a couple’s control that divorce has become rather common. Though divorce rates have been slowing down over the past several years, people are still doing what they can to avoid it — be it marrying the right person, waiting until the right age, or deferring until financial security is solidified.
All of those things may help you avoid a divorce, but we now have even more insight into what can make an otherwise strong union fracture. And it has more to do with the economy than with Tinder profiles, Facebook flirting, or too much time at the bar or in front of the Xbox.
According to a study published in American Sociological Review, the biggest factor leading to divorce is the husband’s job status. Harvard researcher Alexandra Killewald crunched the numbers and found that men who didn’t have jobs, or who had been out of work for a long time had a statistically higher chance of getting divorced in any given year, compared to those with stable careers.
Many couples fight about money, and that is often a leading factor in divorce proceedings. But this study goes a little deeper and adds another layer of complexity to those financial issues. Per Killewald’s study, men without jobs increase their odds of divorce by roughly 30%.

Divorce and employment status

A fired man leaves his job
Unemployed businessman | Source: iStock
The research looks at data dating back 46 years to the 1970s and found that for men who were not employed full-time, there was a 3.3% chance they would get divorced in any given year. Compare that to men who did have a full-time job during the same time period, and the chances dropped to 2.5%. That’s what was found from looking at more than 6,300 couples.
“For marriages formed after 1975, husbands’ lack of full-time employment is associated with higher risk of divorce, but neither wives’ full-time employment nor wives’ share of household labor is associated with divorce risk,” the study says. “Expectations of wives’ homemaking may have eroded, but the husband breadwinner norm persists.”
Those are a couple of other interesting details that the study unearthed — that the full-time job status of the wife and the division of household labor didn’t have a significant impact on divorce risk. Instead, the real difference had to do with the husband’s job status.
“It is possible that husbands’ less than fulltime employment is associated with marital disruption more strongly than wives’, not because of gendered interpretations of lack of full-time employment, but because husbands’ part-time employment or nonemployment is more likely to be involuntary,” the study says. “Involuntary nonemployment may negatively affect marriages more strongly than voluntary nonemployment.”
In other words, it’s not just being out of work; it’s being fired or laid off, and not being able to find a job.

Dodging divorce

Wedding rings
Wedding rings | iStock
There are limitations to the study, as Killewald points out. It didn’t include same-sex couples (marriage data hasn’t existed for very long), and it didn’t include men who chose to become stay-at-home dads, and let their wives be the household breadwinner. Read through the study to get a full picture of Killewald’s other concerns. There is also evidence out there that division of labor in the household and a wife’s employment status can play a bigger part in divorce than this study claims.
But what you really need to know is that there was a clear correlation with employment status and divorce rates.
What does this mean for you and your relationship? It might not mean anything — each and every marriage and relationship is different. But we’ve known for a long time that many marriages fail due to financial problems, and the employment status of the husband clearly plays into that.
And perhaps most importantly, there are innumerable other factors that can lead to divorce that aren’t necessarily taken into account by this study. Cultural differences, religion, children — a marriage can be wrecked by any number of things, not merely the fact that someone loses their job. But a connection exists, according to Killewald’s work, and if you want to stay out of divorce court, you should first try to stay out of the unemployment office.

Culled from Money & Career Cheat Sheet:
Friday, 10 February 2017

5 Lamest Retirement Excuses People Tell Themselves -Sheiresa Ngo


Planning for retirement is a smart thing to do. However, it’s not always the most enjoyable activity. Reaching your retirement savings goal requires some sacrifice now so that you can enjoy life later. Even though getting ready for your golden years means you’ll have to give up some things today, you’ll thank yourself in a few years. However, not everyone thinks this way. Less than half of workers in the United States (48%) said they and/or their spouse have never attempted to calculate how much money they’ll need so they can live comfortably during retirement, according to an Employee Benefit Research Institute survey.
Instead of focusing on the results, some people make excuses for why they can’t save for retirement. Here are five of the lamest retirement excuses people tell themselves.

1. I’ll work until I die

iZombie
iZombie | The CW
If you reason that you can just put off retirement savings because you plan to work until you die at your desk, you might want to rethink that plan. The odds of being physically unable to work at some point in your life are higher that you might expect. Roughly 1 in 4 of today’s 20-year-olds will become disabled before they have a chance to retire, according to the U.S. Social Security Administration. Sadly, many millennials say they expect to work until they draw their last breath. A survey of adults aged 20 to 34 conducted by Manpower Group found that about 20% of millennials believe they will have to work until their dying day.

2. I need to save for my kids’ college education

glass jar full of coins displaying college
College fund | iStock.com
Your kids can get a scholarship for college. You, on the other hand, can’t get a scholarship for retirement. In addition, your child can choose a less expensive option for school or take on a side job. Transfer some of the responsibility for college financing to your children. It will teach them a bit of responsibility. The best gift you can give your children is to not be a burden on them when you’re older. In this situation it’s best to put yourself ahead of the kids. Don’t feel guilty, they’ll appreciate it later. Financial adviser Pedro Silva says many people put other major expenses before retirement and never get around to saving for the future.
People often cite car payments, child care expenses, credit card, or college debt as primary concerns and retirement saving as something to be done later. There is no way to make up for lost years of retirement savings, and those who can afford to save the additional amount later often take on too much risk to make up for the time lost. We often picture our lives in the future as being different; we will exercise, we will eat better, spend more time with our families, clean out the basement, etc. The truth is the changes you wish to make have to start today. Make a to-do list and write “call HR to start 401(K). Once that is done, move on to the next item, realizing you are in control and making choices to shape your future in the direction you want to go.

3. I’ll save when I make more money

Young woman thinking about paying bills
Paying bills | iStock.com
Time is quickly ticking away. If you wait until you make more money, you might be waiting for a very long time. Raises and promotions aren’t guaranteed (neither is your job), so you might as well go ahead and start socking away some cash now. The longer you wait to save, the less time your money has to grow, so it’s wise to start saving as soon as possible. If you delay saving for retirement until you’re 35 years old, you’ll need to save more than 16% of your income each year just to produce the same potential retirement income at the age of 65 as a worker who started saving 10% of their income starting at 30 years old, according to the Insured Retirement Institute. If you decide to wait until 40 years old, you would have to save more than 26% of your income.

4. I can’t afford to save for retirement

wallet full of money
Money in a wallet | iStock.com
Saving for retirement means you’ll have to give up some comforts right now, but you really can’t afford not to save for retirement. If your finances are tight, work on developing a budget so that you can make room for retirement savings. Your future survival could depend on it.
Howard Dvorkin, CPA and Chairman of Debt.com said the people who claim to not be able to afford retirement are usually the ones who are wearing most of their money in the form of expensive purchases:
The lamest excuses I always hear are the unsaid ones. I meet someone who tells me they simply can’t afford to save for retirement, as they look at their Omega wristwatch and climb into their leased BMW so they can pack for their vacation to the Bahamas. Yes, many Americans are struggling and simply have trouble making ends meet, and I respect and work with them. But I meet many other Americans who earn quite enough to meet all their obligations – but they spend frivolously without ever admitting it to themselves.

5. I don’t know how much to save

Thinking young woman looking up at many question marks
Thinking young woman looking up at many question marks | iStock.com/SIphotography
There are plenty of retirement tools available that can help you figure out how much cash to put away. This is one of the worst excuses for not building your nest egg. These tools allow you to create a retirement budget, figure out life insurance needs, estimate retirement income, and more. As a general rule of thumb, you should aim to have at least one times your salary saved by age 30, three times by age 40, seven times by age 55 and 10 times your salary by the time you reach 67 years of age, according to Fidelity.

Culled from Money & Career Cheat sheet

Wednesday, 8 February 2017

Obaseki signs 2017 Budget, Pension Bills into law - Usman A. Bello,

Obaseki signs 2017 Budget, Pension Bills into law
Governor Godwin Obaseki of Edo State


Governor Godwin Obaseki of Edo State yesterday signed the 2017 appropriation Bill into law.
The governor who also signed the Pension Bill into law, said he would organise the implementation of the Contributory Pension Scheme.
Governor Obaseki who commended the legislators for the ‘speedy’ passage of the budget, said, “Last year when I presented this bill to you for consideration, we were very clear that there were certain key principles and budget policies, which we showed would lead to significant changes in our economy. This early passage will help the process.”
On the pension bill, he said the state government had already commenced implementation of the Contributory Pension Scheme since January and that with the signing of the Pension Bill, what was left was to start settling arrears.

Culled from Daily Trust

Friday, 3 February 2017

One Millennial Money Habit That All Retirees Should Adopt - Dan Kadlec

 
Scroll back up to restore default view.


We all have “senior moments” and briefly forget a name, something at the store, or even why we went downstairs in the first place. Such a slip-up might be embarrassing or disconcerting, but it usually doesn’t cost anything—unless the moment is financial in nature, such as forgetting to pay a bill. In that case, online bill payment can be a lifesaver.
A quarter of Americans pay their bills late and the top reason—cited by 61% of late payers in one survey—is that they simply forgot. The No. 3 reason is they lost the bill and No. 5 is that they procrastinated past the due date.
In each of those cases, online bill payment is an easy fix. With bank payment tools and many other apps you can enter a payment in any amount the day you get a bill, and choose the day you want to make the payment. Done. No forgetting. No lost bills. No procrastination issues.
Better still, you can set automatic monthly payments for recurring charges like a mortgage or car payment. You may want to set automatic minimum monthly payments for a regularly used credit card—so that you won’t incur a late fee if you miss a payment. (You will, however, suffer an interest charge if the balance is not paid in full.)
Another benefit that can be especially valuable for seniors: Getting and paying bills online makes it easier if you are a snowbird or own a vacation home and split time between two residences.
Yet while online bill paying has become increasingly popular, millions still pay what they owe the old-fashioned way and risk the costs of forgetfulness.
Consumers paid a record $3.9 trillion in monthly bills last year, according to a report from electronic payments firm ACI Worldwide and research firm Aite Group. There has been a clear shift towards online payments since 2010, according to the report.
More than eight billion bills—56% of all bills—are now paid online via a biller, bank or third-party website, according to the report. Bills paid by check have fallen 20% while bills paid by credit card—typically online—have doubled.
As you might expect, younger generations are leading the shift. Just 15% of millennials’ bills are paid by mail; for seniors, that figure is 40%, according to the report. Millennials pay 61% of their bills online while seniors pay 42% of their bills online.
The clear trend is for more online payments among all generations. That’s a good thing as the convenience and flexibility are unrivaled—to say nothing of the costs of buying checks, envelopes and stamps. But retirees should bear in mind that going electronic also means they should make certain a loved one or trusted individual has access to their digital accounts in case of disability or death.

Yahoo Finance

Thursday, 2 February 2017

'I'm 32 and want to travel. Can my £500k flat fund my retirement?' -Amelia Murray


Tony Patterson
Tony Patterson has itchy feet and a 'tiny' pension - is selling his home the answer? Credit: Rii Schroer
Tony Patterson is at a crossroads.
At 32, the newly qualified primary schoolteacher has "itchy feet" and is considering selling his £500,000 two-bedroom flat in Shadwell, east London, and working abroad when his mortgage expires in August.
Mr Patterson does not know how long he will be away for - it could be two years or 10 - but he wants to think long-term about his financial future.
He wants "security" when he's 60 and does not want his desire to travel to get in the way of a "decent pension". He says his current teacher's pension is "tiny" at £1,000. He continues to contribute £203 a month towards it.
Mr Patterson earns £28,000 a year and has £5,000 in cash savings. His only investment is his property, which he bought nine years ago as part of the Government's Help to Buy scheme.
Tony Patterson
Mr Patterson wants to ensure he has enough in savings to buy another London property when he is finished travelling Credit: Rii Schroer
He bought a 35pc share at 23 while he was working in insurance. When his salary increased five years ago he bought the remaining 65pc. In total the flat cost him £265,000, and his mortgage has £240,000 outstanding.
If he sells his property he believes he will have around £250,000 to invest. Ideally this will be income yielding to supplement his salary when he finds teaching work in Europe or Asia.
When Mr Patterson eventually returns to the UK he wants to have enough saved for a "decent deposit", of 30pc to 40pc, to buy another London property.
So he wants his investment to grow in line with property prices. He also wants to ensure he does not hamper his future retirement.
£Average house price: a 50-year journeyAverage house priceQ1 1966Q1 1984Q1 2002Q2 1968Q3 1970Q4 1972Q1 1975Q2 1977Q3 1979Q4 1981Q2 1986Q3 1988Q4 1990Q1 1993Q2 1995Q3 1997Q4 1999Q2 2004Q3 2006Q4 2008Q1 2011Q2 2013Q3 2015050k100k150k200k250kHighcharts.com/Nationwide Building Society
Mr Patterson has considered letting out his property for £1,800 a month, as he did when he taught in Japan for 18 months, although he said the experience was quite stressful.
He is also unsure if a lender would consider him for a buy-to-let mortgage if he is travelling.

Hayley North, chartered financial planner at Rose & North, said:

Mr Patterson needs first of all to determine his priorities.
He would ideally like to be saving for the long term towards his pension, own a London property and build some capital while topping up his income.
These are conflicting priorities and he certainly cannot achieve all of them at once.
If his key priority is pension income, he needs to make the most of his opportunity to contribute more now while he is earning in the UK. Mr Patterson's current pension is extremely small and will in no way support him when he retires.
Once he stops earning in the UK his annual allowance for tax-relievable contributions will reduce from his current salary of £28,000 gross to £3,600, which will make retiring at 60 very challenging.

If we assume a mid-range attitude to investment risk is taken and a 4.8pc annual growth rate on pension investments, net of charges, then over 28 years, if Mr Patterson invests the minimum £3,600 into a pension each year, he might end up with £217,706 before inflation.
This would not yield more than about £8,700 in annual income, assuming a 4pc annuity rate.
The pension he has built up as teacher is currently very small and if he does not plan to work in the United Kingdom for a while, there are no guarantees that he will continue to grow this.
To save for the future, sacrifices do have to be made when you are earning money in earlier years.
In this case, a long period abroad not earning very much and with limited pension contributions could cost him dearly in the long run.
If he does decide to sell his property, it would be prudent for him to make a large one-off pension contribution with some of the proceedsSebastian Hurst, Plutus Wealth
However, it seems that another of Mr Patterson's priorities is to own a property in London.
The only way to guarantee this is to keep his current property. This might be difficult if he can't find a suitable lender, even though the numbers stack up.
A standard residential mortgage would typically have a ''consent to let'' option, permitting the property to be let for a short period for, say, a year of travelling.
If Mr Patterson wants to go travelling for any extended period, it is likely that he would need to sell the property or remortgage.
Buy-to-let mortgage rules have become much stricter in recent months.
A typical lender will now insist that the rental income Mr Patterson receives is equal to at least 145pc of any mortgage payment at a rate of 5.5pc.
This would mean he would need rental income of £1,595 per month as a minimum to make this work. As he expects to be able to obtain £1,800 this might work.
Conservatively, and not taking account of the actual interest rate he might pay, which could be lower than 5.5pc, Mr Patterson might then have net monthly income of around £700 before any costs, such as letting agent fees, which would both cover his excess income requirements and allow him to save towards a pension, for example.
If Mr Patterson's priority is to travel, then he might have to sacrifice saving while he is away and make up for lost time later on.

Sebastian Hurst, chartered financial planner at Plutus Wealth, said:

Like all people, Mr Patterson wants ample income to live a comfortable life, sufficient capital to fund his short and medium-term goals and a large nest egg to retire on.
His short-term goal is income and his medium-term goal is capital. His ability to achieve these goals is a decision between either renting out his current property or selling and investing the proceeds.
The situation regarding Mr Patterson's pension savings is much clearer.
If he moves abroad, he won't have any "relevant UK pensionable earnings" and he will thus only receive tax relief to a maximum of £3,600 gross or £2,880 net.
While he may still have an income in the UK from his buy-to-let or other investments, these do not constitute "relevant UK earnings" and he thus will not receive any tax relief on this income.
Mr Patterson's pension is alarmingly small and he is extremely unprepared for potential retirement at age 60.
If he does decide to sell his property, it would be prudent for him to make a large one-off pension contribution with some of the proceeds.
The idea would be to make a pension contribution that matches his gross income for that financial year.
For example, if he sells in April 2017 and his gross earnings for the financial year are £28,000, he can make pension contributions of £22,400.
This would give him tax relief of £5,600. He could repeat this exercise when he is back in the UK. However, this will affect his deposit amount for a future property purchase.
Mr Patterson should carefully weigh up the experiences he wants to have while abroad, and the length of time he will be overseas.
Property will be a limiting factor, as it may not generate a steady income, due to interest rates and other variables. But this may also provide financial discipline not to deplete his capital.
If Mr Patterson can secure a competitive fixed-rate mortgage and rent out his property, he should adopt this approach.
If, however, he is forced to move on to the lender's standard variable rate (SVR) he should sell the flat, invest the proceeds into a diversified portfolio of funds such as Standard Life My Folio Managed 3 and consider making large ad hoc pension contributions.
Mr Patterson will struggle to get a buy-to-let mortgage as most lenders require applicants to own at least one other property.
Moving abroad will complicate matters further.
He may want to consider keeping his current standard residential mortgage and apply for a "consent to let" from his current lender.
Lenders may keep the rate as it is, add an additional 1 percentage point to the current residential mortgage rate or charge the SVR for doing so.
Mr Patterson should look for a good quality letting agent, which will typically charge around 10pc to 15pc of the rent received.
On the lender's SVR, at a rate of say 4.5pc, Mr Patterson's net profit from the property will be around £7,470 a year.
On a more competitive fixed rate, of say 2.25pc, his net profit will be £12,532. Both scenarios offer sufficient income as he intends to work while away.

Culled from Telegraph
Obaseki appoints 15 Pension Fund Administrators On February 2, 20174:29 amIn NewsComments By Esther Omoye GOVERNOR Godwin Obaseki of Edo State has appointed 15 Pension Fund Administrators, PFAs, to undertake the enrolment of employees in the state public service, in line with his budget speech where he promised that the contributory pension scheme would commence in 2017. The PFAs, according to a statement by Mr. John Mayaki, Interim Chief Press Secretary to Governor Obaseki, are Trusftfund Pensions Plc, Aiico Pension Managers Limited, ARM Pension Managers (PFA) Limited, Crusader Sterling Pensions Limited, Fidelity Pension Managers Limited, First Guarantee Pensions Limited and Future Unity Glanvils Pensions Limited. Governor of Edo State, Mr Godwin Obaseki Others are Leadway Pension PFA Limited, Legacy Pension Managers Limited, Pensions Alliance Limited (PAL), Sigma Pensions Limited, Stanbic IBTC Pension Managers Limited, Premium Pension Limited, OAK Pensions and NLPC Pension Managers Limited. According to the statement, in addition, an executive bill for the amendment of the pension law had been proposed to the Edo State House of Assembly. Governor Obaseki said the scheme, aimed at addressing the challenges of the old defined pension benefit would commence in January 2017. Meanwhile, the governor also revealed that government would resolve teething key issues identified in the payment of pensions and gratuities, adding: “The issue of pension is one that we will deal with. The government has made provision in the budget for the scheme, with the contribution of 10 per cent by government and 8% per cent by workers.” The Governor however called on workers and other relevant stakeholders to support government in the actualization and realization of the scheme for the benefit of all.

Read more at: http://www.vanguardngr.com/2017/02/obaseki-appoints-15-pension-fund-administrators/

Wednesday, 1 February 2017

Fed Govt remits N13.2b pension contribution-Omobola Tolu-Kusimo and Bukola Bolajoko


Fed Govt remits N13.2b pension contribution
The Federal Government has released N10.3 billion for payment of pension contributions to pensioners, who retired in November and December 2015, The Nation has gathered.
The government also released N2.9 billion to be paid to other batches of retirees, bringing the  amount released to N13.2 billion.
Consequently, the Central Bank of Nigeria (CBN) has paid the monies to Pension Fund Administrators (PFAs), who have commenced payment to retirees some of who confirmed the receipt of such payments to The Nation.
Findings have shown that the last Federal Government retirees  to receive pension after retirement were those who retired in October 2015.
This is because retirement benefits payment, which is the last stage of the Contributory Pension Scheme (CPS), has witnessed some setbacks in recent times due to Federal Government’s inability to remit pension contributions and pay accrued rights.
Head of Benefits and Insurance Department, National Pension Commission (PenCom), Lana Loyinmi, affirmed that payments were being made to the retirees.
Loyinmi, however, said the Commission was working with the government agencies that are the direct employers of workers to ensure that more funds are released for payment of accrued pension.
He said: “We are liasing with the government and engaging agencies that are direct employers of these retirees. Retirees from the private sector on the other hand do not have a problem with receiving their pension.
“Part of the challenges of the scheme has been delayed remittance of accrued pension right by federal government in recent times.”
He noted that the way forward is continued engagement of relevant agencies for the release of outstanding accrued rights while steps are taken to alleviate the waiting of retirees before the release of accrued rights.
“Under the institutional framework of the CPS, the employer is mandated to contribute 10 per cent while employee contributes eight per cent of employee’s annual emolument into the Retirement Savings Account (RSAs),” he added.
Interim Association of Contributory Pension Scheme Pensioners President, Comrade Matthew Shittu, confirmed that PFAs have started paying their pensions.
He appealed to PenCom  to continue to prevail on the government to pay retirees under the CPS their retirement benefits while they are still alive.
He said if the government had released funds for November and December 2015 retirees, it should also release funds for last year’s retirees too.

Culled from Nation